News Break
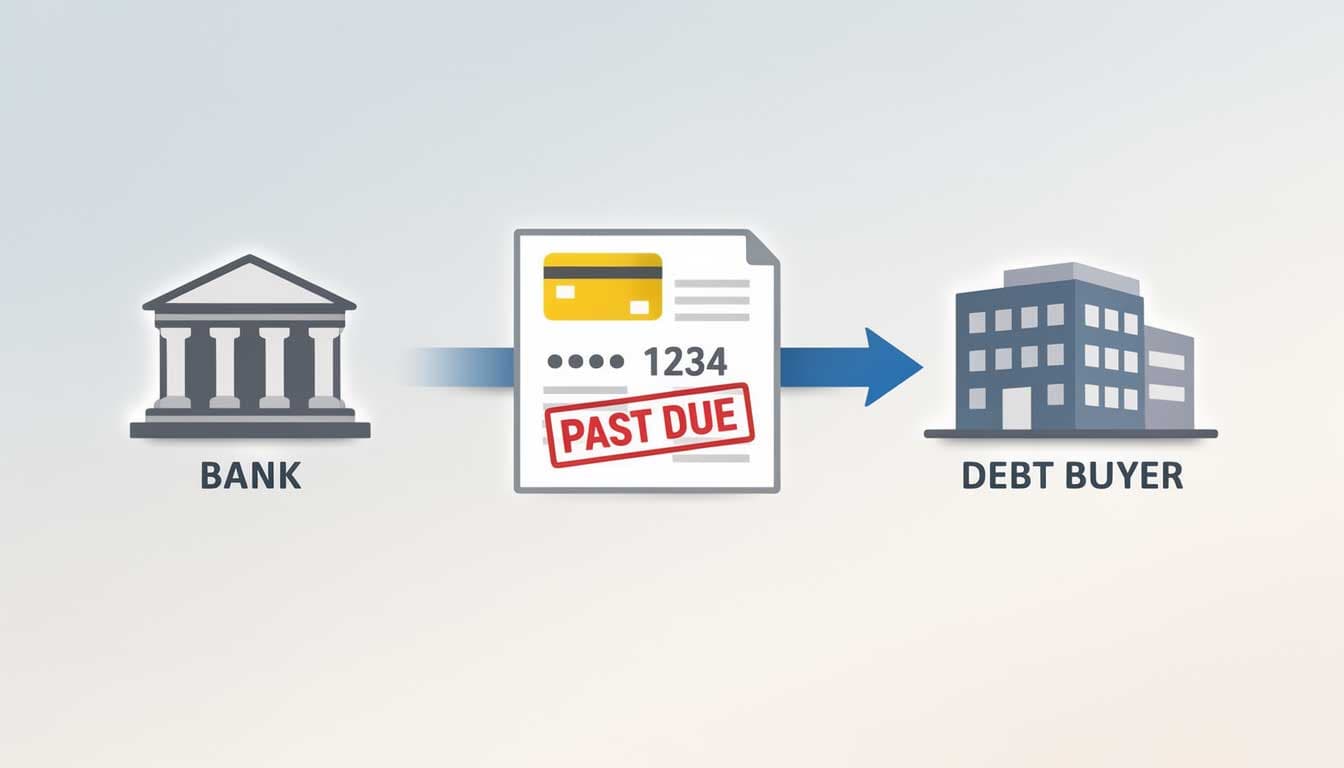
Credit Card Debt Collection: How Banks Sell Your Account
March 16, 2026
Blog / News Break
Stop debt collector harassment stop now! Learn FDCPA rights, cease letters, validation, and Texas laws to silence collectors legally.
Debt collector harassment stop is something you can legally force — and faster than you might think.
Here's the short answer:
Debt collection problems are among the most common consumer complaints filed with federal agencies. And it's not hard to see why.
The calls come early. They come late. Sometimes they come to your workplace. The stress is real — and according to consumer advocates, harassment from debt collectors has contributed to bankruptcies, job losses, and serious emotional harm for many people.
But here's what most people don't know: you have powerful legal rights under the Fair Debt Collection Practices Act (FDCPA). This federal law makes harassment, threats, and abusive tactics by third-party debt collectors illegal. And it gives you concrete tools to make it stop.
This guide will walk you through exactly how to use those rights — step by step.
The first step in fighting back is knowing when a line has been crossed. Debt collectors often count on the fact that you don't know the rules. They might sound authoritative or even scary, but they are bound by strict federal regulations.
Under 15 U.S. Code Section 1692d, a debt collector is prohibited from engaging in any conduct the natural consequence of which is to harass, oppress, or abuse any person. This isn't just a suggestion; it's the law.
One of the most common forms of harassment is the "phone bombardment." However, the Consumer Financial Protection Bureau (CFPB) has established clear frequency limits. Generally, a collector cannot call you more than seven times within a seven-day period regarding a specific debt. Furthermore, once they have had a telephone conversation with you, they must wait at least seven days before calling again about that same debt.
Timing also matters. Legally, they can only call you during "convenient" hours, which are defined as 8 a.m. to 9 p.m. your local time. If your phone is ringing at 6 a.m. or 11 p.m., they are breaking the law.
If a collector uses obscene or profane language, they are in violation. But even more common are "false threats." This includes:
If you want the phone to stop ringing, you have to move the conversation from the phone to the mailbox. Verbal requests to "stop calling" are often ignored because they are hard to prove in court. To achieve a permanent debt collector harassment stop, you need a paper trail.
The FDCPA gives you the right to demand that a third-party debt collector stop contacting you entirely. To do this, you must send a "Cease Communication" or "Cease and Desist" letter.
When writing this letter, you don't need to be a legal scholar. You simply need to state that you want them to stop all further communication with you. You can find more details on handling these situations in our guide on Struggling with Debt Collectors.
This is the most critical part of the process: Send the letter via Certified Mail with a Return Receipt requested. This provides you with a "green card" signed by someone at the collection agency, proving exactly when they received your demand. Once they receive this notice, they can only contact you one more time to:
While you wait for the letter to arrive, start a documentation log. Every time they call, write down:
| Feature | Verbal Request | Written Cease Letter |
|---|---|---|
| Legal Weight | Weak / Hard to prove | Strong / Legally binding |
| FDCPA Protection | Limited | Full protection under § 1692c |
| Proof of Delivery | None | Certified Mail Receipt |
| Effectiveness | Low | High |
Debt collectors are allowed to contact third parties (like your neighbors or family) only once, and only to get your "location information" (address and phone number). They are strictly forbidden from telling these people that you owe a debt.
Furthermore, if you tell a collector (verbally or in writing) that your employer prohibits you from receiving personal calls at work, they must stop calling you there immediately.
When a collector first contacts you, they are required by law to provide you with specific information about the debt. This is known as a "validation notice."
Under 15 U.S. Code Section 1692g, the collector must send you a written notice within five days of their initial contact. This notice must include the amount of the debt, the name of the original creditor, and a statement informing you of your right to dispute the debt within 30 days.
If you don't recognize the debt or believe the amount is wrong, you have a 30-day window to send a Debt Validation Letter. Once you send this dispute in writing, the collector must cease all collection activity until they provide you with verification of the debt. This is a powerful tool for a debt collector harassment stop because it forces the collector to prove their claims before they can bother you again.
Many modern validation notices now include electronic forms or "tear-off" sections to make disputing easier. However, we always recommend a custom letter to ensure you are asking the right questions. You need to know exactly what a collector is legally defined as to ensure your rights are protected; check out our article on What is a Debt Collector Under the FDCPA? Your Rights Explained.
A valid notice must break down the debt, showing interest, fees, and payments made. If they can't provide this, they may not have the legal right to collect from you at all.
While the FDCPA is a federal law that applies nationwide, some states offer even stronger protections. Since we operate in Florida and Michigan, it's important to understand the local landscape.
In both Michigan and Florida, state laws supplement the FDCPA. For example, the Michigan Regulation of Collection Practices Act and the Florida Consumer Collection Practices Act (FCCPA) provide similar protections but sometimes extend to the original creditors, not just third-party agencies.
In these states, as in others, there is a "strict liability" standard. This means you don't necessarily have to prove the collector intended to break the law—only that they did. If they violate your rights, you can sue for:
Every state has a "statute of limitations" on debt. This is the time limit during which a creditor can legally sue you to collect. In Michigan, this is generally six years, while in Florida, it is typically five years for written contracts. If a debt is "time-barred" (older than the limit), they can't successfully sue you, though they might still try to call you unless you send a cease letter.
If a collector ignores your cease letter or continues to use illegal tactics, you need to escalate. Filing official complaints creates a public record of their bad behavior and can lead to fines for the agency.
When filing, be specific. Attach your documentation log and a copy of your certified mail receipt. This evidence makes it much harder for the collector to claim "it was just a mistake."
You don't have to live in fear of your phone ringing. The laws are on your side, but you have to be the one to enforce them. By identifying illegal tactics, sending a formal cease letter via certified mail, and demanding debt validation, you can effectively make the harassment stop.
At KillDebt, we believe that everyone deserves a fair fight. Our AI-powered platform, ParkerGPT, was built to give you the tools normally reserved for expensive law firms. Trained by Brian Parker, an attorney with over 30 years of experience in debt defense, ParkerGPT can analyze your documents, provide personalized guidance, and help you generate the exact templates you need to defend your rights in Michigan or Florida.
Whether you're looking for a specific case search or need to know your next legal move, we are here to help you turn the tables on abusive collectors.
Start your debt defense today and take back your peace of mind.
About the author
Brian Parker
I have over 30 years of experience defending consumers against debt collection lawsuits and have seen every tactic, threat, and pressure play that collectors use on the phone. Through KillDebt and ParkerGPT, I have systematized the proven defense strategies that actually work - so consumers can respond from a position of knowledge, not fear. My approach focuses on aggressive legal defense based on documented case success rather than false hope that leads to default judgments.